Photo by Ridofranz from Getty Images via Canva.com
In this article:
Updated 2026
Buying a house involves a lot of moving parts, from preparing your finances and getting pre-approved to finding the right home, making an offer, and closing. For military buyers, PCS timelines, BAH, VA loan eligibility, and the possibility of another move can add another layer to the decision.
Whether you’re a first-time homebuyer or you’ve purchased a home before, understanding the steps to buying a house can make the process easier to navigate. This guide walks you through the home buying process from start to finish.
What Are the Basic Steps to Buying a House?
The home buying process includes:
- Deciding whether buying makes sense for your finances and timing.
- Preparing your finances and determining a realistic budget.
- Getting prequalified or preapproved for a mortgage.
- Choosing a buyer’s real estate agent.
- Researching neighborhoods and finding the right home.
- Comparing home financing options and choosing a home loan.
- Making an offer and negotiating the purchase contract.
- Completing the inspection, appraisal, title work, and mortgage underwriting.
- Conducting a final walkthrough.
- Closing on the home.
- Taking care of important tasks after closing.
Is Now the Right Time to Buy a Home?
Buying a home isn’t automatically the right choice for everyone. Military buyers have additional factors to consider, including the possibility of moving again within a few years, unexpected orders, high-cost duty locations, and changes in BAH.
These considerations, along with expenses such as childcare and commuting, can affect whether buying makes sense right now. Sorting through the financial, practical, and personal reasons behind your decision is an important first step in the home buying process.
Plan Your Exit Strategy
While debating buying vs. renting, you’ll want to consider an exit strategy, especially if this property isn’t your “forever” home. Seasoned real estate agents who regularly work with military buyers are familiar with this scenario and can help you look for a property that fits your future needs, whether that means selling later or buying a home with rental potential for years to come.
Don’t discount the time and dedication it takes to own a rental home business if you’re considering converting your home into a rental property. An agent who also assists landlords can help you learn about topics like rental property taxes and finding the best tenants.
It’s important to note that not every property is suited for future renters or even buyers. For example, a homeowners association may have restrictions on rentals. Or perhaps your family doesn’t mind aircraft noise or another location-specific feature that could be less appealing to future buyers.
Prepare Your Finances Early
Your credit is an important part of mortgage qualification, but lenders also consider factors such as income, existing debt, assets, and the type of loan you’re seeking. Preparing your finances well before you begin house hunting can help you understand what you can comfortably afford and identify any issues that may affect your mortgage options.
Begin to Build and Repair Your Credit
Start by reviewing your credit reports for errors, unfamiliar accounts, or other problems that could affect your ability to qualify for a mortgage. You can currently request free credit reports from Equifax, Experian, and TransUnion through AnnualCreditReport.com. Checking your own credit report doesn’t hurt your credit score.
Credit scores commonly use a range of 300 to 850. While requirements vary by lender and loan type, a score around 620 is usually considered sufficient for a conventional mortgage. FHA loans may allow scores as low as 580 with a 3.5% down payment, while the VA doesn’t set a minimum credit score for VA-backed loans, although individual lenders may establish their own credit requirements.
Review your reports carefully and correct inaccurate information or possible signs of fraud. Your credit history can also help you identify areas to work on before applying for a mortgage, such as high credit card balances or missed payments.
What if you have bad credit?
If you hope to improve your bad credit score, realize that closing an account you don’t use isn’t a quick fix. A closed account will remain on your credit report. Closing an account can reduce your available credit and increase your credit utilization ratio, which may affect your score. However, if that credit card has a high interest rate or tempts you into impulse spending, weigh those factors when deciding if you should close it.
Also, be cautious about opening new credit accounts shortly before applying for a mortgage. A lender’s hard credit inquiry can have a small effect on your score, although multiple mortgage credit checks made within a relatively short shopping window are generally treated as a single inquiry for scoring purposes.
Calculate Housing Payments
You’re probably considering basing your future mortgage on your current rent or current or future BAH. These are good starting points, but your housing budget should reflect the full cost of homeownership and your individual financial situation.
A standard calculation to determine a housing payment is to aim for 28% to 30% of your gross income. But we all know military life rarely fits into a one-size-fits-all category.
Another budgeting option is the 50/30/20 Budget: 50% for needs, 30% for wants, and 20% for savings and other debt. An online mortgage calculator, like the one at Veterans United, can help you predict an affordable mortgage payment.
Don’t forget there are expenses beyond your monthly mortgage payment. A working budget that includes these often-overlooked expenses can help you determine what you can realistically afford.
Include costs such as:
- Utilities
- Homeowners insurance
- Private mortgage insurance, if required
- Property taxes
- HOA dues
- Maintenance and repairs
- Landscaping, pool maintenance, or pest control services
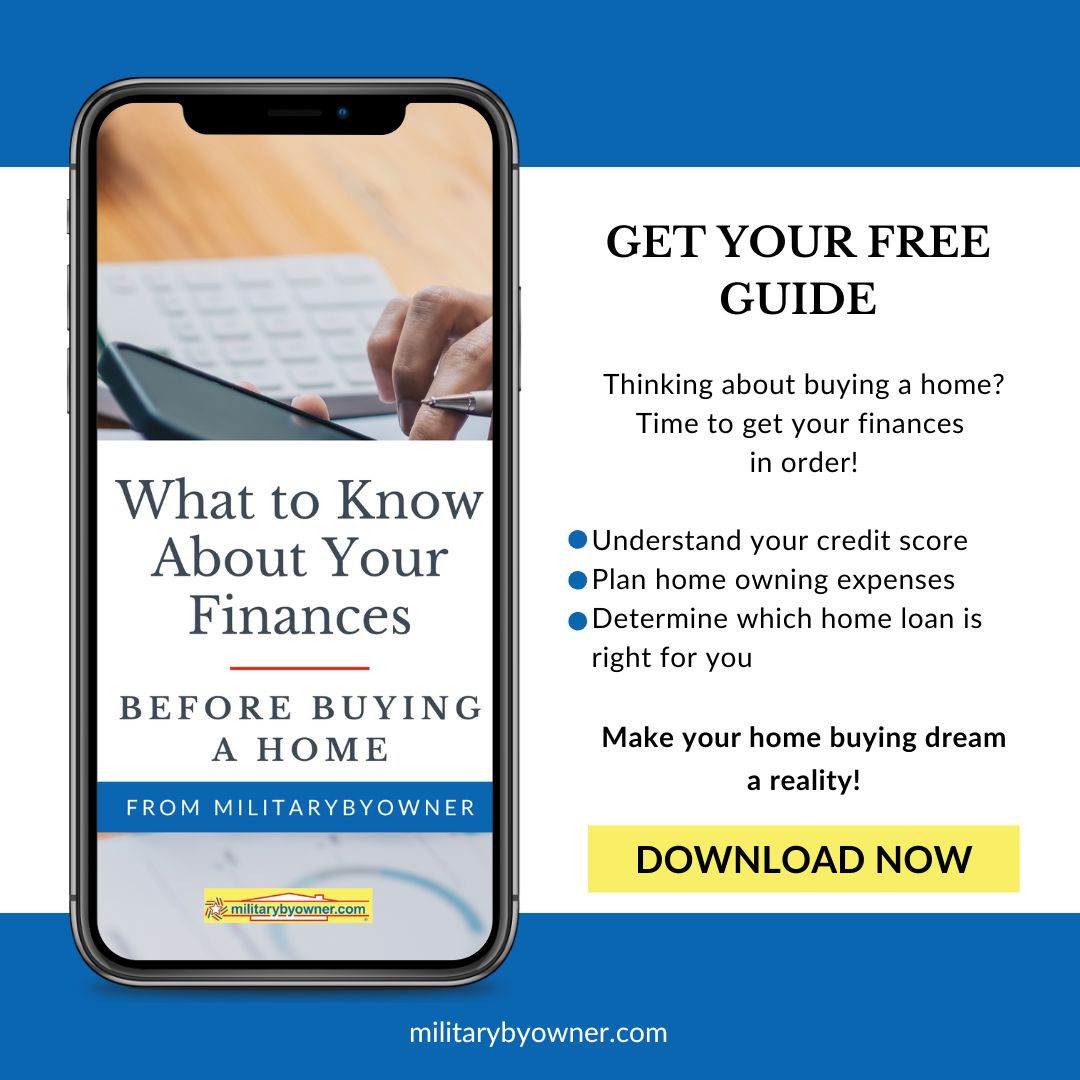
For more in-depth information about preparing your personal finances for a home purchase, see our free guide below, What to Know About Your Finances Before Buying a Home.
Save for Upfront and Ongoing Costs
Before buying, plan for cash reserves to cover both the transaction and expenses that come with owning the home. Depending on your loan and purchase contract, these can include:
Earnest money: A good-faith deposit made according to the purchase contract. If the transaction closes, the deposit is generally credited toward amounts the buyer owes at closing. Whether earnest money is refundable if the transaction falls through depends on the contract and applicable contingencies.
Down payment: The amount you pay toward the home purchase rather than finance. The required amount varies by loan program, and some eligible buyers may have a no-down-payment option..
Closing costs: Fees and expenses associated with obtaining the mortgage and transferring ownership. Your actual closing costs vary by loan, lender, location, and transaction. Sometimes negotiable with the seller.
Immediate renovations: Painting or flooring may be easier before moving in, while inspection findings may reveal more urgent expenses.
Emergency fund: Keep money available for unexpected repairs and other expenses after becoming a homeowner.
Get Prequalified and Preapproved for a Home Loan
After checking your credit scores and reports and making necessary corrections, you can begin talking with mortgage lenders about what you may qualify to borrow.
Mortgage Prequalification vs. Mortgage Preapproval
Although the terms sound similar, they hit two different levels of financial scrutiny.
A prequalification is a self-reported, surface-level look at your finances and gives you an idea of how much mortgage lenders will offer and at what interest rate. Prequalification is not a guarantee for a loan; it’s simply a tool to help you understand your potential buying power. You can usually do this part online.
The results might appear like you can afford more than you previously thought, but realistically, your budget and mortgage lender will reveal your true capacity for a home purchase.
A preapproval is a deeply detailed review of your total financial picture, conducted by a bank. The investigation reviews income sources, debts, credit history, and other factors like your debt-to-income (DTI) ratio to determine whether you’re a reliable candidate for loan repayment. A preapproval shows a home seller you’re serious about buying their house, and it helps move the process along faster if you’re already approved.
In general, the goal is to obtain a lender’s written indication of how much it may be willing to lend based on certain assumptions about your financial situation. This can help establish a realistic price range and show sellers that you’ve already begun the financing process.
When you’re ready to seriously shop for a home, ask prospective lenders what documentation they review and what their preapproval process includes.
Mortgage Prequalification vs. Preapproval: What's the Difference? reveals more information about the differences and how you can obtain each status.
Choose a Buyer’s Real Estate Agent
You aren’t required to use a buyer’s real estate agent, but an experienced agent can help you navigate property searches, contracts, negotiations, deadlines, inspections, and closing. For military buyers, an agent familiar with PCS timelines, VA financing, remote house hunting, and the local market can be especially helpful.
Working with a Buyer’s Agent
A buyer’s agent represents your interests during the home purchase and can help you identify properties, evaluate offers, negotiate terms, and manage the transaction through closing.
Before working with an agent, discuss the terms of the relationship and any written buyer agreement you’ll be asked to sign. Compensation is negotiable and is not set by law. Depending on the agreement and transaction, agent compensation may be structured as a percentage, flat fee, hourly amount, or another clearly defined amount.
Finding a Military-Friendly Real Estate Professional
- Browse through the professional real estate agents in MilitaryByOwner’s business directory. You can also ask family, friends, and current homeowners in your desired area for their recommendations.
- Ask about the agent’s experience working with military buyers and handling PCS-related timelines..
- Consider a real estate agent with the Military Relocation Professional designation. This agent has undergone specialized training related to the specific challenges military families face during the buying process.
- Ask about experience with VA-financed transactions if you plan to use a VA loan.
- Discuss communication preferences and availability, particularly if you’ll be house hunting remotely.
The goal is to find an experienced agent you’ll feel comfortable working with and who can understand your priorities.
Questions to Ask Your Agent
You’ll have dozens of questions along the way, but before you hire an agent, ask questions that help you decide whether the relationship is a good fit.
1. What is your personal experience with military relocation and PCS details?
Ask for examples of how the agent has handled military-specific challenges, such as short PCS timelines, remote home buying, or other military life specifics.
2. How much experience do you have working with a military buyer in this market location?
Hyper-local knowledge, especially about the real estate market surrounding the military base, can be valuable.
3. Are you comfortable working with a VA loan?
An agent who’s handled VA-financed transactions should understand how the VA appraisal and other loan requirements can affect the purchase timeline.
4. How much availability do you offer? What is your communication style?
These are important questions for every buyer, but especially those buying sight unseen or moving from OCONUS.
Photo by Monkey Business Images from Canva.com
Research Neighborhoods and Start House Hunting
It’s hard not to immediately start scrolling through properties once you’ve decided buying a home is the right thing to do. But researching the location is just as important as evaluating the house itself.
Clearly Explain Your Housing Priorities to Your Agent
No one knows your household’s priorities better than you. Your buyer’s agent can help with the search, but you’ll also want to research the factors that matter most to you, including commute times, schools, taxes, HOA restrictions, nearby amenities, and neighborhood characteristics.
Research Crime, Schools, and Other Neighborhood Factors
Crime and Safety Factors
Most home buyers’ top housing priority is neighborhood security. But questions such as “Is this a safe neighborhood?” or “Is this a good school?” call for more than an agent’s personal opinion. HUD has clarified that sharing objective school-quality or crime-rate information isn’t automatically a Fair Housing Act violation. But agents must still avoid subjective statements based on protected characteristics, so reliable third-party sources are useful when researching neighborhoods.
Most agents will point to general websites like Niche.com and Community Crime Map to help you make your own decisions based on data. You can also find helpful reviews from other military families at Military Town Advisor.
Safety matters, but other quality-of-life factors can make or break a home search. Doing your homework early lets you quickly share your top priorities with your agent. Common topics for you to explore include:
- Commute to work and school. A long, expensive commute from the installation may negate any purchase savings. If possible, check your likely route during normal commute times.
- Taxes and HOA costs. You might think you’re comfortable paying the predicted mortgage, but also factor in local taxes and HOA fees.
- School qualities and ratings. For some families, a top-ranked school is everything. For others, specific services for special needs children are the most important factors. Narrow your must-haves for school choice.
- Resale and rental potential. Five-and ten-year plans are common in military life. Will this home fit your plan for future resale or rental opportunities? Also discuss if selling this home unexpectedly after two or three years still makes the purchase feasible.
- House features. Sometimes a fixer-upper isn’t in the cards for a military buyer because of an upcoming deployment. Communicate these restrictions to your agent, along with other high-priority features like the number of bedrooms and bathrooms, a garage, and a backyard.
Choose a Home Loan
Military buyers have several home financing options to consider. A VA home loan can offer significant benefits to eligible borrowers, but it’s worth comparing it with conventional, FHA, USDA, and other available loans based on your finances, the property, and current mortgage rates.
VA Home Loans
A VA-backed purchase loan may allow an eligible borrower to buy without a down payment as long as the sales price doesn’t exceed the appraised value, and the VA program doesn’t require monthly private mortgage insurance.
Borrowers must still qualify with an approved lender and meet VA and lender requirements.
Basic Eligibility
VA loan eligibility depends on factors such as service history, duty status, and other VA requirements. Eligible borrowers also need a Certificate of Eligibility (COE) and must meet the lender’s requirements for credit, income, and other underwriting criteria.
Your COE also provides information about your VA loan entitlement. Borrowers with full entitlement generally aren’t subject to VA county loan limits, but lenders still determine how much a borrower can afford based on factors such as income, debts, assets, and credit history. Borrowers with remaining rather than full entitlement may encounter different limits.
The VA Loan Funding Fee
In order to keep the VA loan program up and running, the VA adds a funding fee to process the loan, usually 0.5% to 3.3% of the total loan amount. The exact amount depends on a few factors, including whether you’ve used a VA loan before, the loan type, and the size of your down payment. You can check the VA’s funding fee chart for more information.
Some borrowers are exempt from the funding fee, including certain veterans receiving or eligible for VA compensation for a service-connected disability, certain Purple Heart recipients, and qualifying surviving spouses.
VA Loan Appraisal
A VA-financed purchase requires a VA appraisal. The appraisal helps establish the property’s value and determines whether it meets applicable VA Minimum Property Requirements.
A VA appraisal is not a home inspection. The appraisal serves the loan process, while an independent home inspection gives the buyer a more detailed assessment of the home’s physical condition.
FHA and USDA Loans
Other government-backed loan programs may also be worth considering:
FHA Loan: Qualified borrowers may be able to purchase with a down payment as low as 3.5%, depending on credit and other eligibility requirements.
USDA Loan: Qualified borrowers purchasing eligible properties may have access to 100% financing. Income, property, and other eligibility requirements apply.
Conventional Loans
Although most military members consider a VA loan first, other loan options are available. Some conventional loans could be better for your finances, especially if you have a large down payment. Conventional loans aren’t government-backed like VA loans; private lenders back them. If you go the conventional route, you'll learn about:
- Conforming mortgages: These follow guidelines set by government-sponsored enterprises like Fannie Mae and Freddie Mac.
- Non-conforming loans or “jumbo” loans: They’re used for higher-than-usual home loan amounts.
Compare Mortgage Rates and Loan Costs
As you consider loan options, remember you can compare mortgage rates, lending fees, and other loan costs to save money upfront and over the life of the loan. Your agent will probably suggest local mortgage lenders they like to work with, but it's ultimately up to you to choose the loan structure and the loan officer you like best.
back to top
Make an Offer on a Home
You’ve found a home that fits your budget and needs. After reviewing comparable properties and discussing a reasonable offer price with your agent, it’s time to make a formal offer. The seller might accept, reject, or counter your offer.
If the seller counters, you and your agent can discuss possible changes to price, closing date, seller concessions, or other terms.
Real Estate Contingencies
Real estate contingencies are conditions in the purchase contract that can protect a buyer if certain parts of the transaction don’t go as planned. Which contingencies are appropriate depends on the property, local market, financing, and your individual situation.
Common examples include:
1. Financing contingency: Buyers can back out of the deal if financing doesn’t come through.
2. Home inspection contingency: Ensures that the buyer is comfortable with the house’s condition. Sometimes waived during a heated sellers market.
3. Appraisal contingency: Protects the buyer if the property’s appraised value comes in below the purchase price.
4. Home sale contingency: Buyers use this to allow time to sell their current home and use the proceeds to buy a new one. Also often waived during a hot sellers market.
5. Title contingency: Gives buyers an out if a problem with title problem occurs, such as an unknown lien.
6. Homeowners insurance contingency: Buyers like this contingency because it allows them to withdraw from the purchase if an insurance company finds the home uninsurable.
Earnest Money
Once the seller accepts the offer and the parties enter into a purchase contract, the buyer typically deposits earnest money according to the agreement. This good-faith deposit is held in escrow until closing.
Whether the buyer is entitled to a refund if the transaction falls through depends on the contract, applicable contingencies, deadlines, and circumstances.
Photo by Liudmila Chernetska from Getty Images via Canva.com
What Happens After Your Offer Is Accepted?
After your offer is accepted, the transaction moves into due diligence and final loan approval. The next phase generally includes disclosures, inspections, the appraisal, title work, homeowners insurance, mortgage underwriting, and preparation for closing.
Review Disclosures and Arrange for Inspections
Your purchase contract and location will affect which documents you receive and when you receive them. Review everything carefully and ask questions about anything you don’t understand.
Your agent will guide you through the appraisal, disclosures, and inspections that lead to final lender approval. During this timeframe, you’ll have the opportunity to analyze various documents, such as flood maps, geological surveys, and private property ordinances.
Home Inspection vs. Appraisal
A home inspection evaluates the physical condition of the property for the buyer. An appraisal provides an independent opinion of the property’s value for the lender and financing process.
A buyer who is financing a home will generally encounter both, but they serve different purposes.
Order a Home Inspection
A professional home inspection provides an independent assessment of the home’s physical condition. Inspectors evaluate visible and accessible components such as the roof, foundation, electrical system, plumbing, heating and cooling systems, windows, and other features.
The inspection doesn’t guarantee that every component of the house is in perfect condition, but it can identify defects or areas that may need further evaluation.
If the inspection uncovers problems, your options depend on the purchase contract and inspection contingency. You may be able to request repairs, negotiate other terms, obtain specialized inspections, or terminate the agreement within the applicable deadlines.
Home Appraisal
The lender usually arranges an appraisal to evaluate the property’s value. If the appraised value comes in below the purchase price, the buyer may need to discuss options such as renegotiating the price, challenging or requesting reconsideration of the valuation when appropriate, paying some of the difference, or using an appraisal contingency if the contract provides one.
If using a VA loan, know that part of the appraisal process includes checking for Minimum Property Requirements (MPRs) mentioned above in the mortgage section. These ensure health and safety minimums like structural integrity and adequate sanitation, but MPRs don’t cover all the details a home inspection will catch.
Disclosure Statement
Seller-disclosure requirements vary by state and sometimes by the type of property or transaction. Depending on applicable law, sellers may be required to disclose known defects or other information about the property.
Read the disclosures carefully and compare them with what you learn through your own inspections and research. If you find conflicting information or a significant undisclosed issue, talk with your agent and, if necessary, a qualified real estate attorney about your options.
An “as-is” sale generally means the seller doesn’t plan to make repairs or provide certain warranties about the property’s condition. It does not automatically eliminate disclosure obligations imposed by state or federal law.
Your ability to renegotiate or terminate a purchase after discovering a problem depends on your contract, contingencies, applicable law, and timing.
Buying a home “as is”? Here’s what you need to know.
You’ll want to proceed with caution if the disclosure includes big-ticket improvements, such as:
If these issues are revealed, you can cancel the deal. Your escrow deposit would be returned, and you could walk away. However, if you’re still interested in the home, your agent can help you renegotiate the terms so the seller resolves the outstanding issues or reduces the sales price.
Mortgage Underwriting and Final Loan Approval
A preapproval is not the final mortgage approval. After you have a property under contract, the lender completes underwriting and verifies the financial and property information needed to approve and fund the loan.
You’ll be asked for updated bank statements, pay information, tax documents, explanations of transactions, or other documentation. Respond promptly to requests to avoid unnecessary delays.
While your finances are in review, avoid taking on major new debt, opening new credit accounts, changing your financial situation unnecessarily, or making large purchases without discussing them with your lender. Changes to your credit, debt-to-income ratio, employment, income, or assets can affect final approval.
The lender will also address items such as the appraisal, homeowners insurance, and title requirements before issuing final approval.
Our free guide, Closing On Your New Home, offers more insight on how to appeal to the seller with the perfect dollar amount and ideal closing terms.
Review Your Closing Disclosure and Final Documents
For most mortgages, your lender must provide a Closing Disclosure at least three business days before closing. This document shows the final loan terms, projected payments, closing costs, and cash needed to close. Compare it with your earlier Loan Estimate and ask about unexpected changes.
You may also be able to review other important closing documents in advance, including the promissory note, mortgage or deed of trust, and deed.
Complete the Final Walkthrough
Your last due diligence as the buyer is the final walkthrough. This is not another official inspection, but a final chance to make sure the property is in the condition you initially agreed to.
Take Inventory of the Property
A day or two before the scheduled closing date, you and your agent will take a final tour of the property. During this walkthrough, you’ll inventory what is included with the home, such as appliances, window treatments, or anything else you defined in the contract.
From the inside to the outside, take note of the house’s overall condition and compare it to what you’ve included in your contract. If any detail has been overlooked, your agent will address those concerns with the seller’s agent. If everything around the house meets the contract terms, you can give your approval, and the home buying process moves toward closing day.
Homeowners Association Disclosure
If the property is part of a homeowners or condo association, review the association’s governing documents, fees, restrictions, and any available financial information before closing. The timing and disclosure requirements vary by state and transaction.
Use our homebuyer walkthrough checklist to make the process easy:
What Happens at Closing?
Closing is the final stage of the home buying process, when you review and sign the documents needed to complete the loan and transfer ownership of the property. You’ll also provide any remaining funds required from you before the transaction can be completed.
Closing Day
Military homebuyers may not always be able to attend closing in person. Depending on the lender, settlement provider, state requirements, and transaction, remote signing or the use of a Power of Attorney may be possible. If a borrower is deployed, traveling, or otherwise unavailable, discuss those options with the lender and closing team well in advance.
Regardless of how or where you sign, this is paperwork related to closing day:
- Photo ID: Either your driver’s license or current passport.
- Down payment: This may be a cashier's check, certified check, or wired money. Before your appointment, you’ll be told the exact amount.
- Closing costs: You'll usually pay 3 to 6% of the loan amount to the lender for processing fees, such as a title search and home appraisal
- Other funds due: You may owe recording fees or other small amounts at closing
- Proof of home insurance: A receipt showing you’ve paid the home insurance policy
- Final purchase and sales contract: Your copy of the paperwork
- Any documents specifically requested by the lender or settlement provider
Your Closing Disclosure provides the final breakdown of these charges and your total Cash to Close. After the required documents are signed, funds are transferred, and the transaction is completed, ownership transfers and you’ll receive possession of the home according to the terms of your contract. Then you can finally celebrate: the home buying process is complete.
What to Do After Closing
You might be ready to start unpacking, painting, or planning renovations, but take care of a few practical tasks first.
- Store your closing and mortgage documents in a secure place where you can access them later.
- Keep your inspection report and familiarize yourself with important home systems, including the electrical panel and water and gas shutoffs.
- Transfer utilities into your name, ideally arranging service before move-in so there is no interruption.
- Update your mailing address and forward your mail with the U.S. Postal Service, using their online process.
- Review upcoming maintenance or repairs and make a plan for both routine and unexpected home expenses.
- Rekey or change exterior locks and update security, garage, and access codes promptly after taking possession.
First-Time Home Buyers: What to Know
If this is your first home purchase, the process can introduce a lot of unfamiliar terms and expenses at once. Start by understanding your complete financial picture rather than focusing only on the home’s purchase price.
First-time buyers should pay particular attention to:
Cash needed upfront: Depending on the loan and contract, you may need funds for earnest money, inspections, a down payment, closing costs, moving expenses, and immediate repairs.
Credit and debt: Your credit history and existing debts can affect both loan approval and the mortgage terms available to you.
Preapproval: Talk with lenders before serious house hunting so you have a realistic idea of your financing options and price range.
Down-payment options: A 20% down payment is not universally required. Qualified borrowers may have lower-down-payment or no-down-payment options, including eligible VA borrowers.
Closing costs: These are separate from the down payment and should be included in your savings plan.
VA loan eligibility: Eligible military and veteran buyers may be able to use a VA-backed loan, but it’s still worth comparing loan options.
Your buyer’s agent: Understand the agent’s role, written buyer agreement, services, and compensation before committing.
Inspection versus appraisal: These are separate processes with different purposes; one does not replace the other.
Closing: Review the Closing Disclosure and other final documents before signing and ask questions about anything you don’t understand
Home Buying FAQs
How long does the home buying process take?
There’s no single timeline for every purchase. How long it takes depends on factors such as your financial preparation, local housing inventory, how quickly you find a home, negotiations, inspection issues, appraisal timing, mortgage underwriting, and the closing schedule. Build flexibility into your timeline, especially for military homebuyers coordinating a purchase with a PCS.
Can military buyers use a VA loan with no down payment?
Eligible borrowers can often use a VA-backed purchase loan without a down payment as long as the sales price doesn’t exceed the property’s appraised value and they meet VA and lender requirements. Some circumstances involving entitlement or the purchase price may affect how much cash is needed.
What are the basic steps to buying a house?
The basic steps include preparing your finances, getting preapproved, choosing an agent, researching homes and neighborhoods, comparing home financing options, making an offer, completing the inspection and appraisal, obtaining final loan approval, conducting the final walkthrough, and closing.
Should I prequalify for a mortgage before looking at homes?
Talking with a lender before serious house hunting can help you understand your likely price range and identify financial issues early. Because lenders use the terms prequalification and preapproval differently, ask what information the lender reviews and what its letter actually represents.
What’s the difference between mortgage prequalification and preapproval?
Lenders use prequalification for a preliminary estimate based primarily on information supplied by the borrower and preapproval for a more detailed review, but lender processes vary. Neither guarantees final mortgage approval.
Do I need a buyer’s agent to buy a house?
Not necessarily, but a buyer’s agent can help with the home search, contracts, negotiations, deadlines, inspections, and closing. If you use an agent, review the buyer agreement carefully and understand what services the agent will provide and how the agent will be compensated.
What’s the difference between a home inspection and an appraisal?
A home inspection evaluates the physical condition of the property for the buyer. An appraisal provides an independent opinion of the home’s value for the mortgage process. A lender generally requires an appraisal when financing a purchase, while an independent inspection helps the buyer evaluate the property’s condition.
Can I back out of buying a house after my offer has been accepted?
Possibly. Your ability to terminate the purchase agreement—and whether you can recover your earnest money—depends on the contract, applicable contingencies, deadlines, and state law.
What happens at closing when you buy a house?
At closing, you review and sign the final documents needed to complete the mortgage and transfer ownership, provide any funds required from you, and complete the settlement process. For most covered mortgage transactions, you should receive a Closing Disclosure at least three business days beforehand so you have time to review the final loan terms and costs.
Buying a home is a major decision, and military life can add unique considerations to every stage of the process. Taking the time to understand your financing, research the property and location, and plan for a future PCS can help you make a more informed purchase.
MilitaryByOwner understands your need to prepare for homeownership. We encourage you to browse our articles, blogs, and home-buying guides. We’re happy to offer guidance and support as you find a home of your own.
Download our free home buying guide below.
MilitaryByOwner has helped military families navigate housing and relocation decisions since 2000. Explore additional PCS resources, military housing guides, and relocation tools designed specifically for military life.
back to top